Reconstructing the International Tax System An Alternative to Pillar One
Source-based taxation and the arms length standard have been foundational elements of the international tax system for many decades. With the advent of the highly digitalized platform firm, the OECD and many other stakeholders assert that these principles have been rendered obsolete. In their stead, these stakeholders have p......
fra 1 199,-
På lager i 1 butikker
Kjøp på nett
Fjernlager
Frakt og levering
Sammenligning av produkter
Her finner du de fire mest populære produktene i denne kategorien i en lignende prisklasse som det du ser på nå.
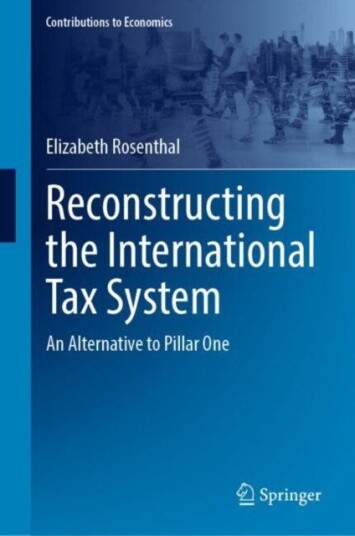
Reconstructing the International Tax System An Alternative to Pillar One
1 199,-
Produktinformasjon
<p>Source-based taxation and the arm’s length standard have been foundational elements of the international tax system for many decades. With the advent of the highly digitalized platform firm, the OECD and many other stakeholders assert that these principles have been rendered obsolete. In their stead, these stakeholders have proposed an alternative hybrid international tax system. Under this proposed hybrid system, the long-standing profit allocation rules would be applied in the first instance to determine the preliminary attribution of in-scope multinational firms’ taxable income to individual taxing jurisdictions. These results would then be subject to a secondary reallocation designed to ensure that a portion of such firms’ taxable income is attributed to, and taxable by, jurisdictions in which consumers and users reside (“market jurisdictions”). This secondary allocation – the core of the OECD’s Pillar One and an essential element of its two-pronged “Pillar One-Pillar Two Solution” – explicitly deviates from both the arm’s length standard and the principle of source-based taxation. </p>
<p>For many reasons, examined in this book, the OECD’s Pillar One would not provide for the effective taxation of highly digitalized platform firms, and, by extension, it would not stabilize the international tax system. The author argues that source-based taxation and the arm’s length standard are entirely compatible with the attribution of a portion of highly digitalized platform firms’ taxable income to market jurisdictions. However, new transfer pricing methodologies and a revised definition of ‘control’ for transfer pricing purposes are required to achieve this result. Combining important findings and insights from academic research in a variety of fields with the author’s extensive practical experience in both public and private spheres, this book is appropriate for academics as well as private sector advisors in the fields of transfer pricing and international tax, chief financial officers of multinational corporations and tax policy analysts.</p>
Topplisten: Other Brand Bøker
Spesifikasjon
| Produkt | |
|---|---|
| Produktnavn | Reconstructing the International Tax System An Alternative to Pillar One |
| Merke | Other Brand |
FAQ
Black Friday er fredag 27. november 2026. Sammenlign prisen på Reconstructing the International Tax System An Alternative to Pillar One hos flere butikker, og sjekk prishistorikken der den er tilgjengelig. Kontroller at tilbudene gjelder samme modell og variant, og ta med fraktkostnaden når du sammenligner.
Populære produkter
Pris og prishistorikk
Akkurat nå er 1 199,- den billigste prisen for Reconstructing the International Tax System An Alternative to Pillar One blant 1 butikker hos Prisradar. Sjekk også vår topp 5-rangering av beste bøker for å være sikker på at du gjør det beste kjøpet.
Effective After-Action Reviews for Emergency ManagersEffective After-Action Reviews for Emergency ManagersMy Busiest Book Ever!: Scholastic Early LearnersHaunting of the Ghost Dragon: A Branches Book (Dragon Masters #27)
Handbook of Environmental EngineeringAutomotive FDI in Emerging EuropeAn Integrative Model of Moral DeliberationGlobalisation and Change in Forest Ownership and Forest Use
Business Strategies and Competitiveness in Times of CrisisGame Theory and Minorities in American LiteraturePoverty, Income and Social ProtectionSky Raiders